The Rise of the Corporate Monoculture: How Chain Restaurants Are Reshaping the American Dining Landscape

The modern American commercial landscape is undergoing a profound structural transformation, driven by the aggressive expansion of major corporate sit-down restaurant chains. Brands such as Olive Garden, Texas Roadhouse, Applebee’s, and The Cheesecake Factory are systematically consolidating market share across suburban strips and urban centers alike. While these establishments have long relied on culinary familiarity, consistent execution, and pervasive marketing to attract broad demographics, their post-pandemic resurgence has accelerated a troubling trend. As independent eateries struggle against insurmountable economic headwinds, the unchecked growth of these corporate entities threatens to erase regional culinary diversity and homogenize community identities nationwide.
The Vulnerability of Independent Dining
For decades, independent restaurants have operated on razor-thin margins, highly susceptible to macroeconomic volatility. Long before the disruptions of the COVID-19 pandemic, structural pressures weighed heavily on non-chain establishments. A landmark 2012 report issued by the consumer and retail research firm NPD Group revealed a concerning trajectory for independent operators. Over a three-year period analyzed in the study, independent restaurants accounted for 87 percent of total customer visit losses nationwide. During that same timeframe, approximately 7,158 independent establishments closed their doors across the United States, whereas major chain restaurant networks successfully added 4,511 new units.
Financial analysts specializing in the food and beverage sector quickly recognized that large-scale corporate restaurant groups were uniquely positioned to capitalize on market vacancies. As pandemic-era restrictions and rising operational costs forced record numbers of independent businesses to shutter permanently—with Yelp data indicating that over 60 percent of pandemic-related business closures became permanent by late 2020—corporate chains seized the opportunity to expand their real estate footprints. Industry forecasts by research firm IBIS World highlighted this disparity, projecting an 8.7 percent increase in the market size of full-service chain restaurants in 2022, far exceeding the historical annualized growth rate of 2.2 percent. By that year, the United States market encompassed more than 100,000 full-service chain restaurants, with annual sales projected to surpass $162 billion.
Real Estate Strategy and Corporate Scale
The primary mechanism driving this corporate expansion is unmatched financial scale, which affords large restaurant groups a distinct competitive advantage in the commercial real estate market. When independent operators succumb to rent hikes, labor shortages, and supply chain inflation, available storefronts and prime commercial parcels flood the market. Corporate executives have proven swift in exploiting this real estate glut.
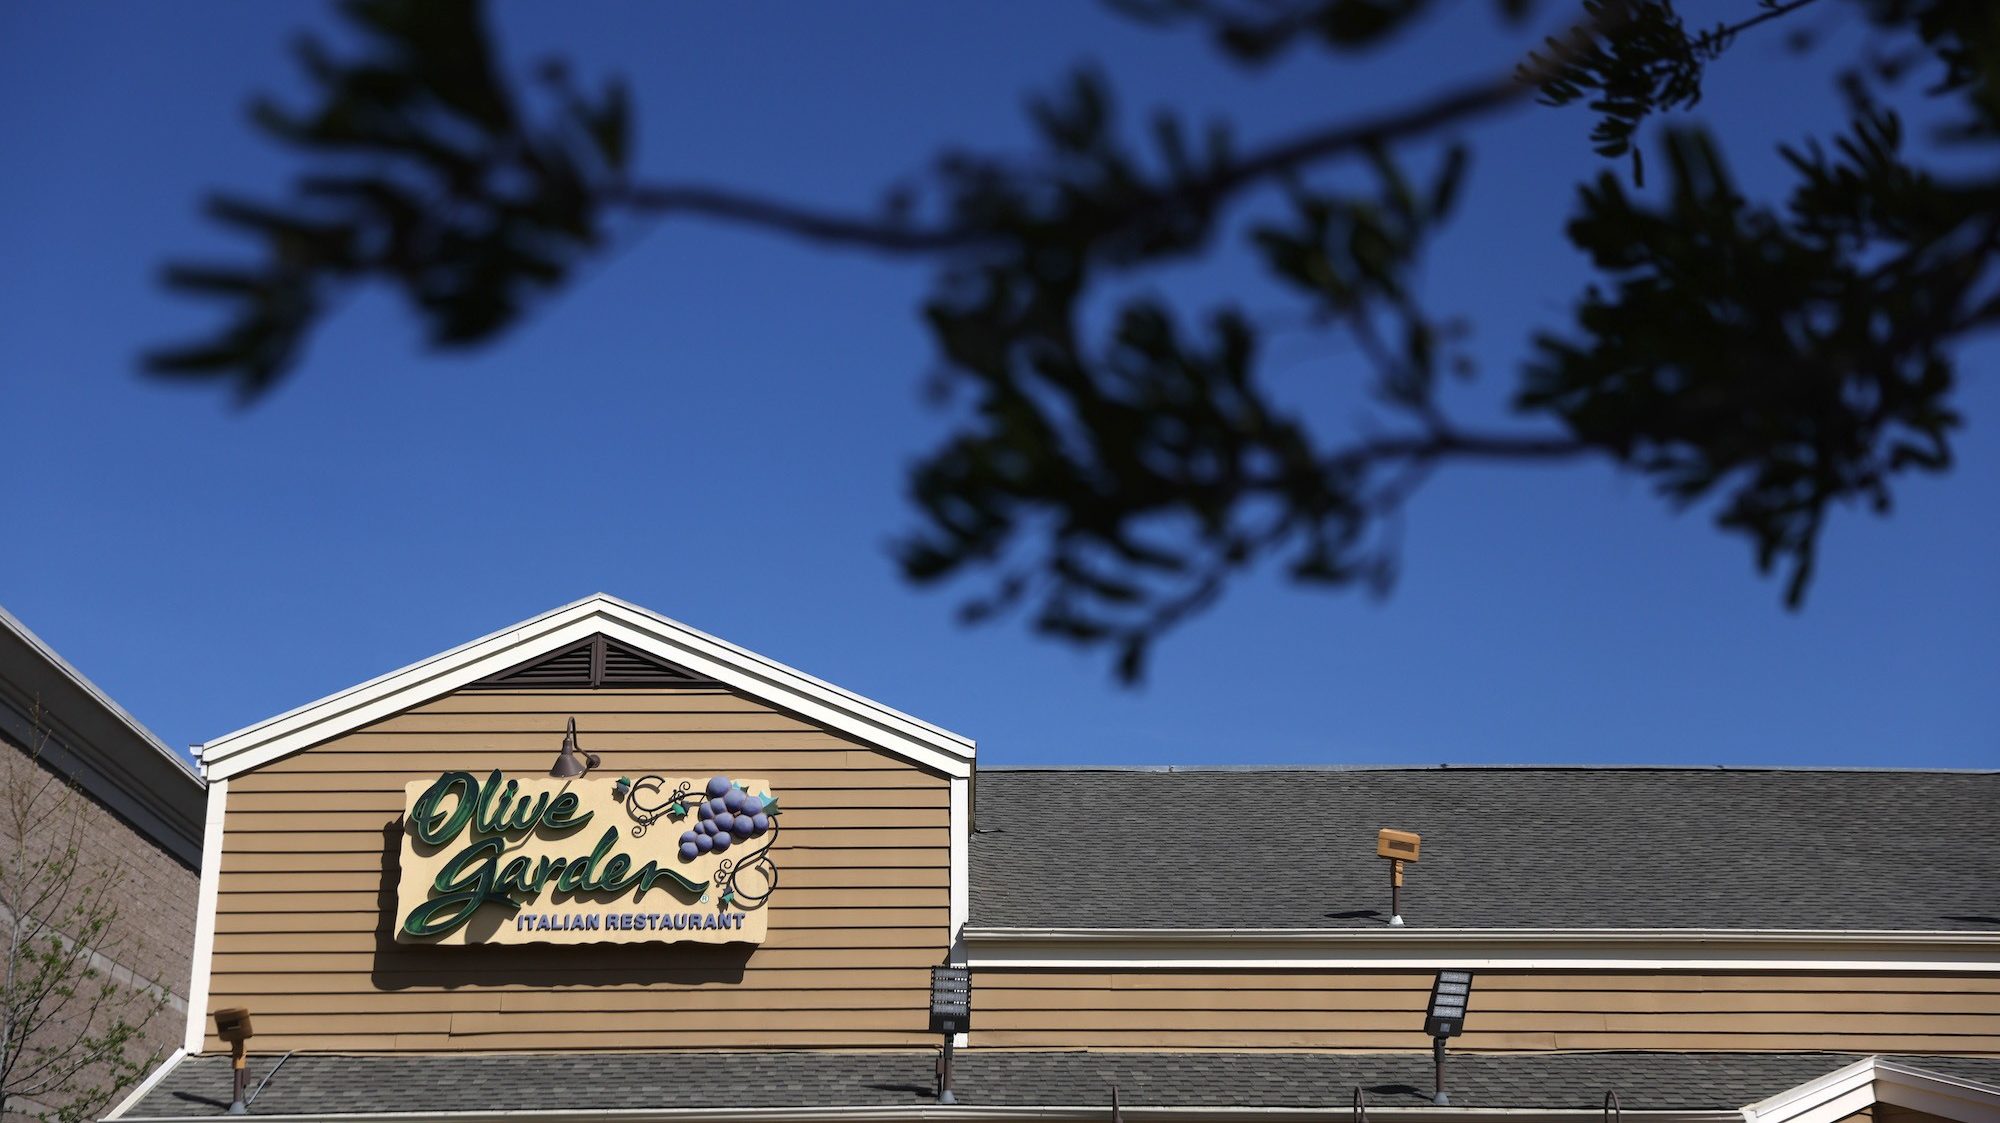
During corporate earnings calls in late 2021 and early 2022, leadership teams from major dining conglomerates openly discussed their aggressive real estate acquisition strategies. John Cywinski, president of Applebee’s parent company Dine Brands, noted that the contraction of the independent restaurant category left significant "white space" for market share acquisition. Similarly, Gene Lee, the outgoing CEO of Darden Restaurants—the parent company of Olive Garden and Longhorn Steakhouse—emphasized the unmatched leverage large brands hold with commercial landlords. Lee remarked that property owners consistently favor the financial security and reliable guarantee of a corporate Darden signature on a lease over unproven local operators.
This aggressive real estate acquisition strategy is essential for corporate growth. Because mature, established restaurant locations typically experience single-digit year-over-year same-store sales growth, brands must continually open new physical units to satisfy quarterly shareholder metrics and drive revenue expansion. Consequently, national chains have methodically annexed properties in regions where independent businesses experienced the most severe disruptions.
The Economic and Cultural Implications of Culinary Monoculture
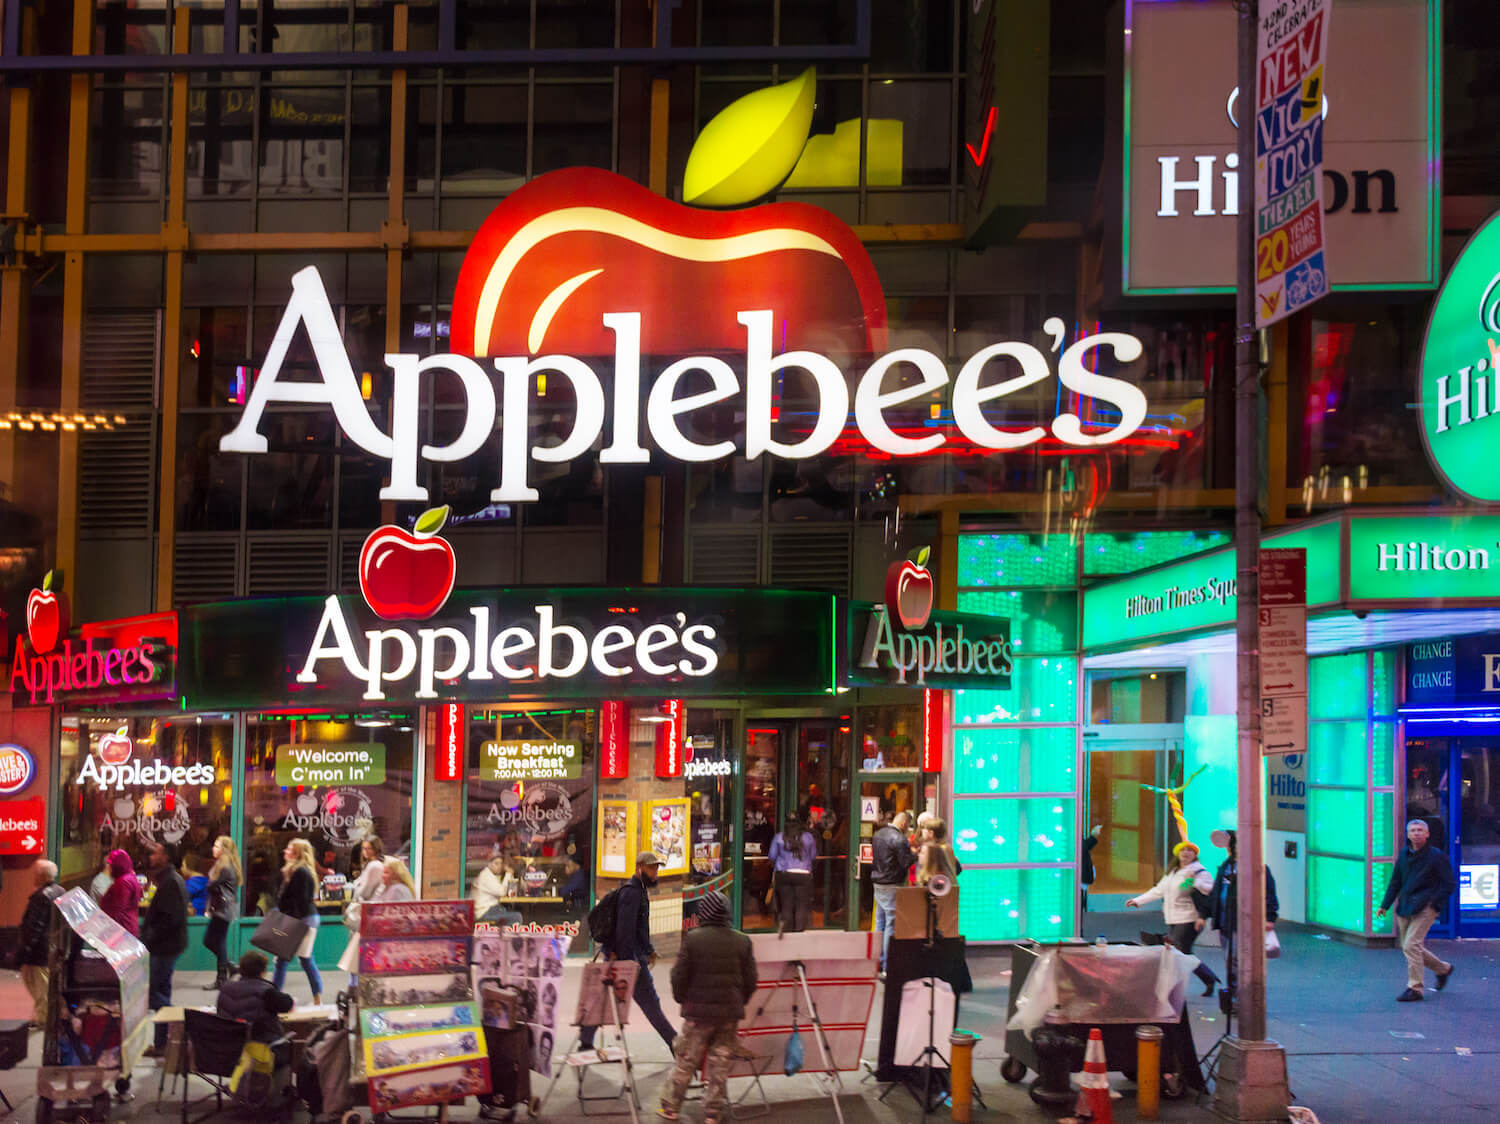
The proliferation of national sit-down chains extends far beyond real estate acquisition; it fundamentally alters consumer behavior and the cultural identity of American communities. Chain restaurants invest billions of dollars annually in marketing campaigns designed to foster a sense of local familiarity and neighborliness. Slogans such as Applebee’s "Eating Good in the Neighborhood" and Olive Garden’s "When You’re Here, You’re Family" construct an illusion of community integration, despite the fact that a significant portion of corporate profits is funneled away from local economies to institutional shareholders rather than being reinvested in the municipality.
Furthermore, the operational standardization that defines corporate chains grants them immense pricing power. By maintaining rigid uniformity in recipes, ingredient sourcing, and portion sizes across hundreds of locations, these brands can incrementally raise menu prices without triggering significant customer attrition. For example, executives from Texas Roadhouse noted that system-wide menu price increases enacted in 2022 had virtually no negative impact on customer traffic or product mix. Independent restaurants, which generally lack the purchasing power and centralized distribution networks of large conglomerates, cannot easily absorb inflationary pressures or match the perceived value proposition offered by national brands without risking customer loss.
This dynamic has given rise to a broader culinary homogenization. Cultural critics and culinary historians note that prolonged exposure to standardized, highly engineered flavor profiles—such as the rich cream sauces and heavy dairy use popularized by mass-market Italian-American chains—can fundamentally reshape consumer expectations of authentic regional cuisine. When corporate facsimiles supplant diverse culinary traditions, the distinct cultural history embedded within a community’s independent dining sector risks being permanently diluted.
Pathways Toward Preservation
The rapid expansion of corporate dining conglomerates mirrors the retail disruption caused by e-commerce giants like Amazon, which systematically replaced localized storefronts with uniform commercial infrastructure. Without deliberate intervention, municipal commercial districts risk losing their distinct character, rendering neighboring towns virtually indistinguishable from one another.
Industry observers and urban planners suggest that countering this trend requires a concerted community effort. Preserving independent culinary ecosystems will likely necessitate municipal policy interventions, such as zoning ordinances designed to limit the concentration of national chains, streamlined permitting processes for local operators, and tax incentives or commercial rent stabilization measures tailored for independent businesses. Ultimately, the future of the American dining landscape depends on conscious consumer choices and legislative frameworks that value regional diversity, local economic resilience, and historical preservation over corporate uniformity.