The Rise of the Culinary Monoculture: How Corporate Restaurant Chains Are Reshaping the American Dining Landscape

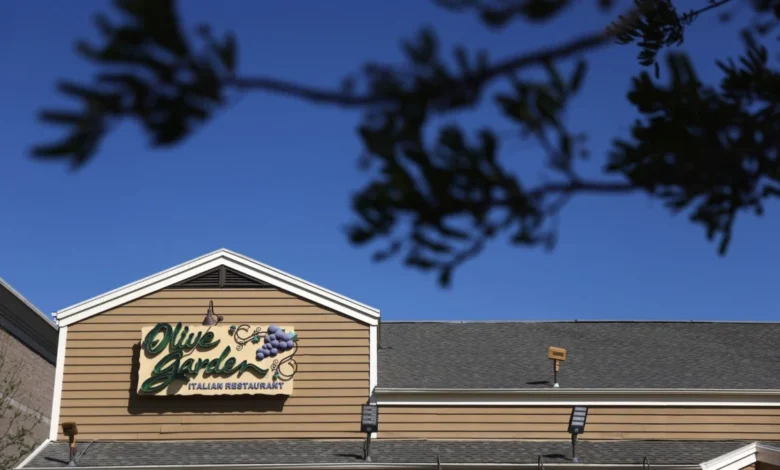
The modern American commercial district is undergoing a profound structural transformation, driven by the aggressive expansion of major corporate sit-down restaurant chains. Brands such as Olive Garden, Applebee’s, Texas Roadhouse, and The Cheesecake Factory are increasingly dominating local real estate markets, capitalizing on a wave of independent restaurant closures accelerated by the COVID-19 pandemic. While these corporate giants offer consumers predictable experiences, reliable pricing, and familiar comfort foods, their expanding footprints pose an existential threat to independent eateries, gradually eroding regional culinary diversity and standardizing the American dining landscape.
Historical Context and the Post-Pandemic Real Estate Shift
The friction between independent eateries and corporate restaurant chains is not a novel phenomenon, but the trajectory of this competitive imbalance shifted dramatically in the wake of public health crises during the early 2020s. Decades prior to the pandemic, warning signs were already evident within the retail and hospitality sectors.
In a comprehensive report issued a decade ago by the consumer and retail research firm NPD Group, data revealed that independent restaurants were losing market share to national chains at an alarming rate. Over a specific three-year observation window, independent operators accounted for 87 percent of total customer visit losses nationwide, with more than 7,100 independent establishments closing their doors permanently. Conversely, major restaurant chains expanded their footprints by thousands of units during the same period, illustrating a structural advantage in supply chain logistics, marketing budgets, and access to capital.
When the COVID-19 pandemic swept across the United States in 2020, it catalyzed an unprecedented wave of business failures. According to data compiled by Yelp, approximately 60 percent of all business closures resulting from the pandemic were permanent, accounting for more than 90,000 restaurants nationwide. This sudden contraction of the independent restaurant sector left thousands of prime commercial storefronts vacant.
Financial analysts quickly recognized that large corporate restaurant groups were uniquely positioned to absorb these vacancies. In late 2020, financial services firm BTIG raised its price targets for publicly traded casual dining stocks, highlighting that industry closures—shouldered predominantly by independent operators—created a lucrative window for national brands to expand into smaller, previously underserved markets.
Leveraging Scale and Real Estate Dominance
The primary advantage held by corporate restaurant groups is scale. While independent restaurateurs often operate on razor-thin margins with limited financial cushions, large parent companies possess robust capital reserves, centralized distribution networks, and sophisticated real estate acquisition teams.
During earnings calls following the height of the pandemic, executives of major restaurant conglomerates openly discussed capitalizing on commercial vacancies. John Cywinski, president of Applebee’s parent company Dine Brands, noted during a quarterly earnings call that the contraction of the broader restaurant category provided a significant opening to capture increased market share. Similarly, Gene Lee, the former CEO of Darden Restaurants—the parent company of Olive Garden, LongHorn Steakhouse, and other major brands—emphasized that landlords routinely favor the financial stability and reliable backing of corporate entities.
"At the end of the day, most landlords want a Darden guarantee signature on their property," Lee stated during an investor conference.
This financial security allows major chains to outbid independent operators for prime real estate. Once secured, these companies deploy standardized operational models that prioritize consistency, operational efficiency, and high volume. By establishing dense networks of locations, corporate chains can amortize marketing and supply chain expenses across hundreds or thousands of units, making it exceedingly difficult for single-unit operators to compete on price or visibility.
Market Data and Financial Performance
Recent economic data underscores the remarkable recovery and expansion of full-service chain restaurants relative to the broader hospitality sector. According to market research firm IBIS World, the market size of full-service chain restaurants in the United States was projected to grow by 8.7 percent, significantly outpacing the historical annualized growth rate of 2.2 percent. The sector currently encompasses more than 100,000 full-service chain locations nationwide, with total annual sales projected to exceed $162 billion.
Furthermore, annual industry reports, such as Technomic’s Top 500 Chain Restaurant survey, indicate that popular full-service dining brands have steadily increased their aggregate share of top-tier market revenue. Individual chains have reported revenues climbing well above pre-pandemic benchmarks. For example, Texas Roadhouse reported a 26 percent increase in revenue by the end of fiscal year 2021 compared to pre-pandemic baselines, prompting the company to accelerate the opening of dozens of new company-owned and franchise locations.
Even strategic shifts intended to optimize corporate profitability have yielded positive financial results. In late 2021, Olive Garden announced the permanent discontinuation of its popular "Never Ending Pasta Bowl" promotion across all domestic locations. Although the promotion had served as a prominent marketing tool intermittently since 1995, Darden leadership noted that customer traffic and profitability remained robust without it. Executives indicated that the brand was sufficiently resilient to maintain high sales volumes without deep-discount promotions, reflecting strong consumer brand loyalty and pricing power.
Consumer Psychology and the Allure of Familiarity
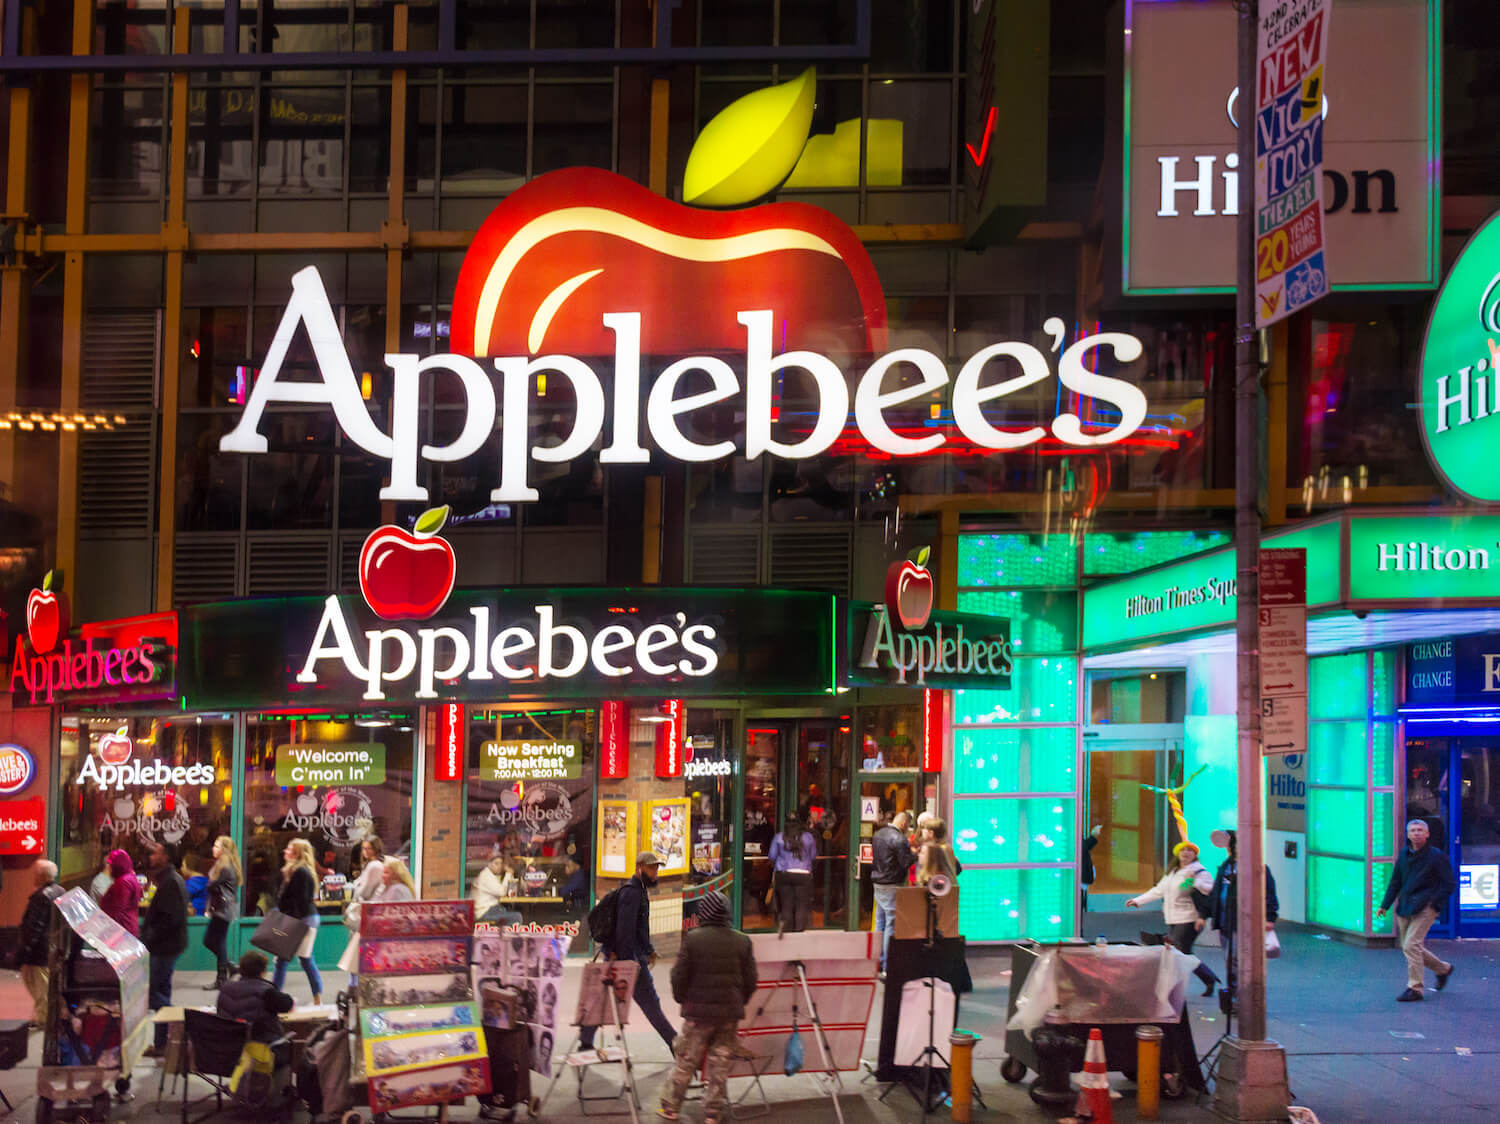
The enduring appeal of chain restaurants relies heavily on psychological comfort and predictability. Culinary critics and cultural analysts have long observed that national chains provide a uniform physical and gastronomic environment that reassures consumers. Regardless of geographic location, a diner stepping into a well-known casual dining establishment encounters identical menus, standardized interior design, and familiar flavor profiles.
This manufacturing precision allows chains to implement incremental menu price adjustments without experiencing significant pushback from consumers. Major restaurant executives routinely report that modest menu price increases—ranging from 2 to 4 percent—have negligible negative impacts on customer traffic or product mix. Diners appear willing to pay a premium for the guaranteed replication of signature items, whether cheddar biscuits, blooming onions, or proprietary dipping sauces.
However, this standardization carries broader cultural implications. Food historians and cultural critics note that widespread reliance on corporate dining concepts can gradually alter consumer perceptions of authentic regional and international cuisines. When industrial, standardized versions of ethnic foods—such as Americanized Italian or pan-Asian dishes—become the baseline reference point for broad demographics, traditional culinary heritage risks being overshadowed by commercial homogenization.
Socioeconomic Implications and Community Impact
The proliferation of national restaurant chains has drawn scrutiny from urban planners, economists, and community advocates concerned with the preservation of local distinctiveness. While corporate chains frequently employ localized marketing campaigns and folksy advertising taglines to foster an illusion of neighborliness, their economic mechanics differ fundamentally from those of independent businesses.
A significant portion of revenues generated by corporate franchise locations is siphoned away from local economies to pay corporate overhead, licensing fees, and shareholder dividends, rather than being reinvested directly into the community. Furthermore, as national brands continue to secure leases in traditional commercial districts and downtown centers, the distinctive character of regional dining scenes diminishes.
Urban retail analysts frequently draw parallels between the restaurant sector and the broader retail industry, where large e-commerce platforms and big-box retailers have systematically displaced independent Main Street merchants. Without proactive municipal interventions—such as targeted zoning ordinances, small-business tax incentives, or protections for local commercial landlords—urban and suburban commercial districts face the ongoing risk of conversion into homogenous corporate corridors.
The long-term trajectory of the American dining landscape hinges on consumer choices and municipal policy decisions. As corporate restaurant conglomerates continue to deploy capital into newly available real estate markets, the preservation of independent culinary culture requires conscious community engagement to ensure that local neighborhoods retain their economic autonomy and unique cultural identity.